Our Story
metronuclear LLC is a deep value investment partnership that awaits then exploits market dislocations, uses algorithms to make investment decisions, and engages management teams to reduce price-value gaps. Originally established to supply physical uranium concentrates to US nuclear plants receiving state-level subsidies, metronuclear invests in both the global nuclear fuel cycle and German companies that are overlooked and undervalued.
Our Journey
Our founder pioneered uranium trading at two global investment banks and later launched metronuclear when New York and Illinois approved annual ratepayer subsidies for nuclear power plants. We have engaged practically every corporate owner of a nuclear power plant fleet in America. While waiting for these corporate owners to diversify their nuclear fuel supply chains, we pivoted to deep value investments, starting with German bank shares (and/or proxies thereof) that traded at historically large discounts to their tangible net asset value, then expanding gradually to shares of other German companies experiencing similar dislocations.
Our Investments
metronuclear has two portfolios: kernkraftfonds (nuclear power fund) and kernwertfonds (core value fund). We use our regenerative capital to make deep value investments in Germany and to trade and invest in a niche commodity market where we believe we have a competitive edge because our founder helped pioneer it.
kernkraftfonds
Through our kernkraftfonds, metronuclear pursues unconstrained trading and investing across the global nuclear fuel cycle in ways traditional investment banks and commodity trading houses cannot. metronuclear deploys proprietary regenerative capital and does not rely on external fundraising. We seek to move flexibly across the entire nuclear fuel cycle to capture value in a manner fully compliant with US Nuclear Regulatory Commission Regulations 10 CFR Part § 40.21. Our founder co‑authored a US patent application for Virtual Nuclear Fuel, which gives us a distinct vantage point in the global nuclear fuel cycle.
kernwertfonds
Through our kernwertfonds, metronuclear makes unconstrained deep value investments in Germany. Our founder’s interest in Germany as a sovereign was shaped by his experience working for its largest bank, Deutsche Bank Aktiengesellschaft, where he built and ran its global uranium trading business.
Deutschland AG
Our prevailing macroeconomic thesis is built on a stronger Germany and a strengthening Europe. The emerging world order, with the United States and China as dominant powers and Europe repositioned as a so-called middle power, reinforces Germany’s role as Europe’s sovereign anchor. Germany has the lowest debt burden in the G7 at around 63 percent of gross domestic product. This gives Germany more fiscal headroom than any other major sovereign to fund remilitarization, digital reindustrialization, and long‑term domestic investment. We believe Europe is moving toward greater strategic autonomy, marking a generational shift that may redirect trade, capital, and security dependencies for decades. While we believe our thesis is compelling, its strongest claims depend on political execution, institutional reform, and behavioral shifts that are ongoing but undone. The potential policy consequences include higher defense spending, more persistent inflation, higher cost of money, and faster progress towards unified savings, banking, and capital markets, all of which may provide a meaningfully more supportive operating environment for European banks.
Commerzbank AG
We view Commerzbank Aktiengesellschaft as one of the purest liquid expressions of our macroeconomic thesis built on a stronger Germany and a strengthening Europe. We believe Commerzbank benefits directly from Germany’s deployment of its fiscal headroom and from the Europe’s shift towards strategic autonomy. metronuclear therefore holds a ultralong term concentrated equity investment in Commerzbank that is around the statutory threshold required under Section 122(2) of the German Stock Corporation Act (§122(2) AktG) to introduce additional items to the agenda of Commerzbank’s Annual General Meetings. metronuclear is very strongly supportive of and in full alignment with the leadership, strategy, and authority of Commerzbank CEO Bettina Orlopp. Commerzbank is Germany’s second-largest listed bank, the market leader in Mittelstand banking, and the parent of leading digital bank and broker comdirect. Its mBank subsidiary is Poland’s fifth-largest bank. And its CommerzVentures venture capital platform invested successfully at an early stage in several fintech unicorns.
UniCredit Società per Azioni, Italy’s largest bank by market value, holds roughly a 42 percent economic stake in Commerzbank. It has launched a voluntary takeover offer and published its transformation and merger blueprint under the title “Commerzbank: A New Chapter.” UniCredit disclosed that about 18 percent of Commerzbank’s outstanding shares were tendered into the offer. metronuclear believes mBank is the quiet catalyst behind UniCredit’s interest in Commerzbank. UniCredit has no meaningful presence in Poland, leaving a critical gap in its self‑styled pan‑European model. Commerzbank’s ownership of mBank fills that gap. UniCredit has stated that it intends to combine Commerzbank with its German subsidiary HypoVereinsbank. A reverse merger is one potential combination path which may unlock significant value for Commerzbank shareholders through lower execution risk, faster synergies, and higher return on tangible equity. metronuclear would therefore vote in favor of a reverse merger at any future Annual or Extraordinary General Meeting if Commerzbank CEO Bettina Orlopp recommends it to shareholders. metronuclear supports Commerzbank’s long term value creation trajectory, whether pursued independently or through a management recommended reverse merger with HypoVereinsbank. metronuclear accepts that UniCredit will determine the appropriate timing and structure of any combination in close consultation with key stakeholders. We also respect Germany’s co‑determination principles and view them as a stabilizing force for long term value creation. Beyond any potential reverse merger horizon, metronuclear intends to remain an ultralong term passive investor in Commerzbank as UniCredit’s own outlook suggests Commerzbank may reach a 25 percent steady‑state return on tangible equity by 2030.
metronuclear believed any one of nine events would over time improve Commerzbank’s fortunes and generate favorable investment returns: (1) reversal of negative euro interest rates; (2) management change; (3) cost optimization; (4) capital optimization; (5) merger or acquisition; and (6) fiscal expansion in Germany; (7) euro appreciation versus the dollar; (8) Commerzbank’s reascension to Germany’s DAX 40 blue-chip index; and (9) positive re-rating of the bank’s shares by the sell-side equity analyst community. All nine events occurred. metronuclear’s original investment in Commerzbank delivered a peak investment return of around 22x inclusive of leverage and is expected over time to deliver annual capital returns (dividends plus share buybacks attributable to our shares) of around 3x the original investment.
Past performance is not indicative of future results. You should not rely on our information to make any investment decisions. Please read our disclaimer.
Other Investments
metronuclear reinvests the regenerative capital returns from our ultralong term investment in Commerzbank into (inter alia) other unconstrained deep value investment opportunities across Germany through our kernwertfonds. To maintain maximum strategic flexibility, metronuclear does not intend to publicly disclose the additional investments we have already made at this time.
Our Team
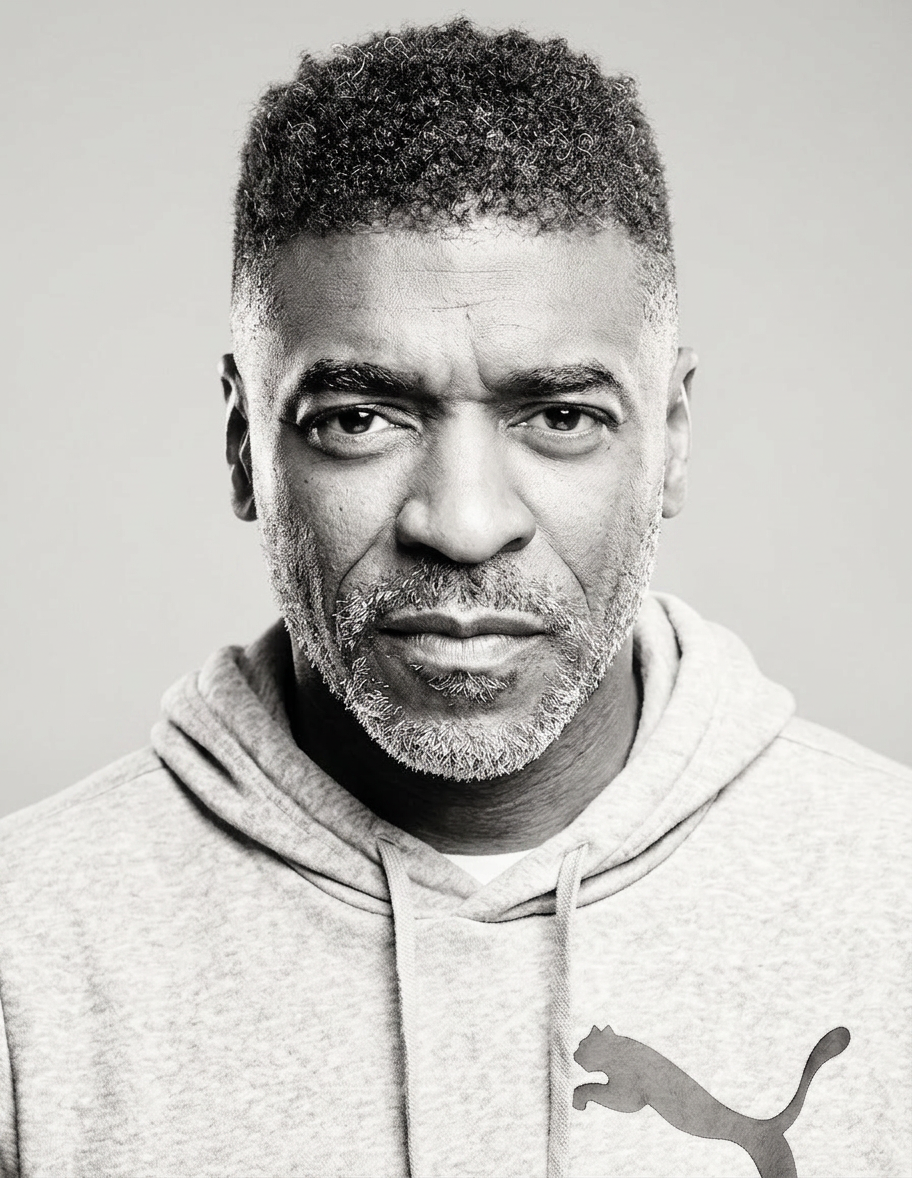
Roy Adams
- Founder and Chief Investment Officer of metronuclear
- Handelsblatt: Scaled investment in Commerzbank, launched #BetOnBettina campaign, and delivered peak investment return of around 22x, with annual capital returns expected to rise to around 3x the original investment.
- Orchestrates the kernkraftfonds (nuclear power fund) and kernwertfonds (core value fund) portfolios
- Trades and invests across the global nuclear fuel cycle for kernkraftfonds with focus on virtualization and tokenization
- Created kernkraftfonds’ uranium term and option pricing models
- Originates, executes, and manages deep value investments for kernwertfonds
- Built kernwertfonds’ deep value algorithms
- Engages investment targets’ management teams to reduce persistent price-value gaps
- Performs fundamental research across all relevant knowledge domains
- Pioneered uranium trading at Deutsche Bank and Lehman Brothers in UK and US with 40+ customers spanning 5 continents
- Financial Times: Adams left Deutsche Bank to work with two non-profits and later to invest privately in uranium miners and European and German banks
- Reuters: Deutsche Bank’s global uranium trading business was long-term supplier of uranium to utilities, profitable each year of its existence, and later sold to Australian bank Macquarie
- Originated and executed first-ever long-term physical uranium supply contract between a bank and a nuclear utility
- Arranged first-ever financially-settled uranium swap with a nuclear utility, covering a quarter of its annual fuel requirements
- Traded first-ever financially-settled uranium swap with institutional investors
- Built uranium-linked structured products portfolio with peak assets under management of 100 million dollars
- Co-authored US patent application for Virtual Nuclear Fuel
- Graduate of NYC Public Schools K-12 (valedictorian at every level), Mathematics and Science for Minority Students Program at Phillips Academy Andover (Honors), Yale University (Varsity Football), and Tuck School of Business at Dartmouth (Edward Tuck Scholar)
- Member of the Board of Directors and Audit & Finance Committee for PENCIL Inc., an educational charity that connects NYC Public School students to success